Family costs, debt push 7 in 10 Kenyans off track for retirement
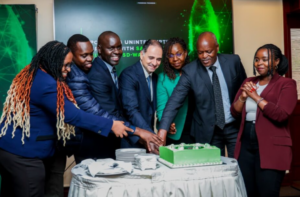
Seven in 10 Kenyans say they are not on track for a comfortable retirement, despite widespread awareness of the importance of saving for later life, according to the inaugural SanlamAllianz Kenya Retirement Benchmark released in Nairobi today.
The study, themed “Kenya Before It Ages”, finds the problem is not understanding; household budgets are stretched, savings leak out when people change jobs, and few know what monthly income their savings will buy.
“Kenya has made remarkable progress in expanding financial access and inclusion. The next challenge is ensuring that financial participation translates into long-term financial security. Retirement should be a stage of life that offers dignity, independence and choice, not one where people are forced to scale back their ambitions,” said Jacqueline Karasha, Chief Executive Officer and Principal Officer, Sanlam Allianz Life Insurance (Kenya) Limited.
Family first, retirement last
Household and family costs are the biggest barrier to saving at 44 per cent, followed by low or irregular income at 37 per cent and debt repayments at 24 per cent. Only four per cent blame a lack of understanding or trust in retirement products.
62 per cent say supporting dependants cuts what they can save, and 39 per cent could cover basic household costs for two months or less if their income stopped today. In the past year, 23 per cent dipped into savings or cut retirement contributions when money was tight, rising to 29 per cent among earners aged 20 to 39.
Cashing out at the exit door
Among respondents who left a job or business holding retirement savings, 53 per cent withdrew at least part of the money and 26 per cent took everything. Only 32 per cent kept or transferred the full amount. A third used the cash to start or support a business or farm.
Yet 65 per cent said they understood the impact at the time, and 53 per cent later regretted the decision. One in five received no help at all when they left.
“The findings show that most Kenyans understand the importance of saving for retirement, yet everyday financial pressures often compete with long-term goals. This is why preservation cannot rely on awareness alone,” said Ms Karasha. “As an industry, we have a responsibility to make it easier for people to stay invested, provide relevant guidance when key decisions arise, and design solutions that reflect the realities of people’s lives.”
Saving without a destination
One in five working-age contributors do not know how much they have saved, and only 29 per cent know the monthly income they will need in retirement. 45 per cent had never heard of income drawdown, yet 51 per cent want a guaranteed monthly income for life.
53 per cent have no funded plan for medical costs after retirement. Remarkably, 88 per cent say they would keep working or run a business even if their retirement income was enough.
“Kenya has made significant progress in building a savings culture, but the next step is turning those savings into sustainable retirement income. Retirement security is ultimately not about the balance someone accumulates during their working years, but whether those savings can provide a reliable income throughout retirement.” said Jonathan Stichbury, Managing Director and Chief Executive Officer, SanlamAllianz Investments Limited.
Beyond the payslip, and a scam warning
Kenya’s economy grew 4.6 per cent in 2025, but the informal sector accounted for 87.2 per cent of new jobs, according to the Kenya National Bureau of Statistics. Among working respondents, 39 per cent say their earnings change from month to month and 51 per cent of informal workers would rather pay in by mobile money.
But digital reach comes with a warning: 45 per cent have lost money or personal information to a digital financial scam, rising to 54 per cent among younger respondents. A trusted provider or regulator tops the list of features that would draw them to a retirement product.
“Kenya has a rare advantage: time. As a relatively young country, we have an opportunity to strengthen retirement preparedness before demographic pressures become more pronounced. Through the SanlamAllianz Kenya Retirement Benchmark, we aim to measure progress, stimulate dialogue and support the decisions needed to improve retirement outcomes for future generations.” said Dr Nyamemba Patrick Tumbo, Group Chief Executive Officer, SanlamAllianz Kenya.
SanlamAllianz will repeat the Benchmark every year to track how these measures move.